In this article, our market research firm analyzes both global and individual agri-food trends. You will find detailed positioning maps that help visualize where countries stand, as well as trends broken down by product type and segment.
The food industry is emerging from 4 years of crises. In 2022, the number of new food products launched worldwide fell by 12.7%. This was the sharpest decline in 30 years. The trend subsequently reversed, with product launches increasing by 15.2% in 2025. In the meantime, eating habits changed direction. More than one in two new products now focus on pleasure, ethical offerings have been cut in half, and private-label brands are capturing most of Europe’s growth.
These figures provide an initial indication of the scale of current food industry trends. But they do not tell the whole story. Drawing on its experience in the food sector, our market research firm has analysed all the available data to provide a concise overview of these trends. In particular, we offer original positioning maps that help explain food trends across products and countries.
Contact the IntoTheMinds research institute
Key Takeaways
- After falling by 12.7% in 2022, new food product launches rebounded by 15.2% worldwide in 2025 and by 31.1% in France (global food innovation barometer).
- Pleasure accounted for 55.7% of global innovations in 2024 (63.8% in France). Ethical innovation has declined significantly.
- Private-label brands reached a 42.4% market share across 6 major European countries (12 months to the end of February 2026) and captured 54% of revenue growth in fast-moving consumer goods.
- Origin remains an important consumer expectation, although attention to it is declining in France.
- Protein and fermentation are driving product offerings: kefir and kombucha sales surged by 149% to 168% in France in 2025.
- Making innovations visible on store shelves remains a major challenge for brands in 2025.
The 16 Identified Food Industry Trends
Below are the 16 trends shaping eating habits, considered in light of what the 2024–2026 data reveal.
These food industry trends are based on a report produced in France by the Ministry of Agriculture, Agrifood and Forestry, which published a forward-looking study on food and eating habits through to 2025 as early as 2017. We thought it would be interesting to compare our assessment of trends in 2026 with the predictions made 10 years ago. Ahead of SIAL, we offer a comprehensive analysis of the food market, assessing developments over the past 24 months and making predictions for the next 24 months.
Let us start with a table of the 16 food industry trends and how they have evolved.
| Trend predicted in 2017 | What the 2024–2026 data show |
|---|---|
| Sustainable food | Consumer expectations remain strong, but the trend is losing ground in product offerings: 69% of consumers worldwide see food choices as an act of civic responsibility (2026), yet ethical considerations accounted for only 3.8% of product launches (2025). |
| Food, health and well-being | Strengthened and increasingly functional: the pursuit of nutritional benefits (38%) overtook food safety (35%) in 2026, while products promising “energy and well-being” gained 5.1 percentage points between 2021 and 2025. |
| Specific diets and communities | Confirmed: 56% of French consumers expect restaurants to offer menus compatible with a range of dietary requirements (2026). |
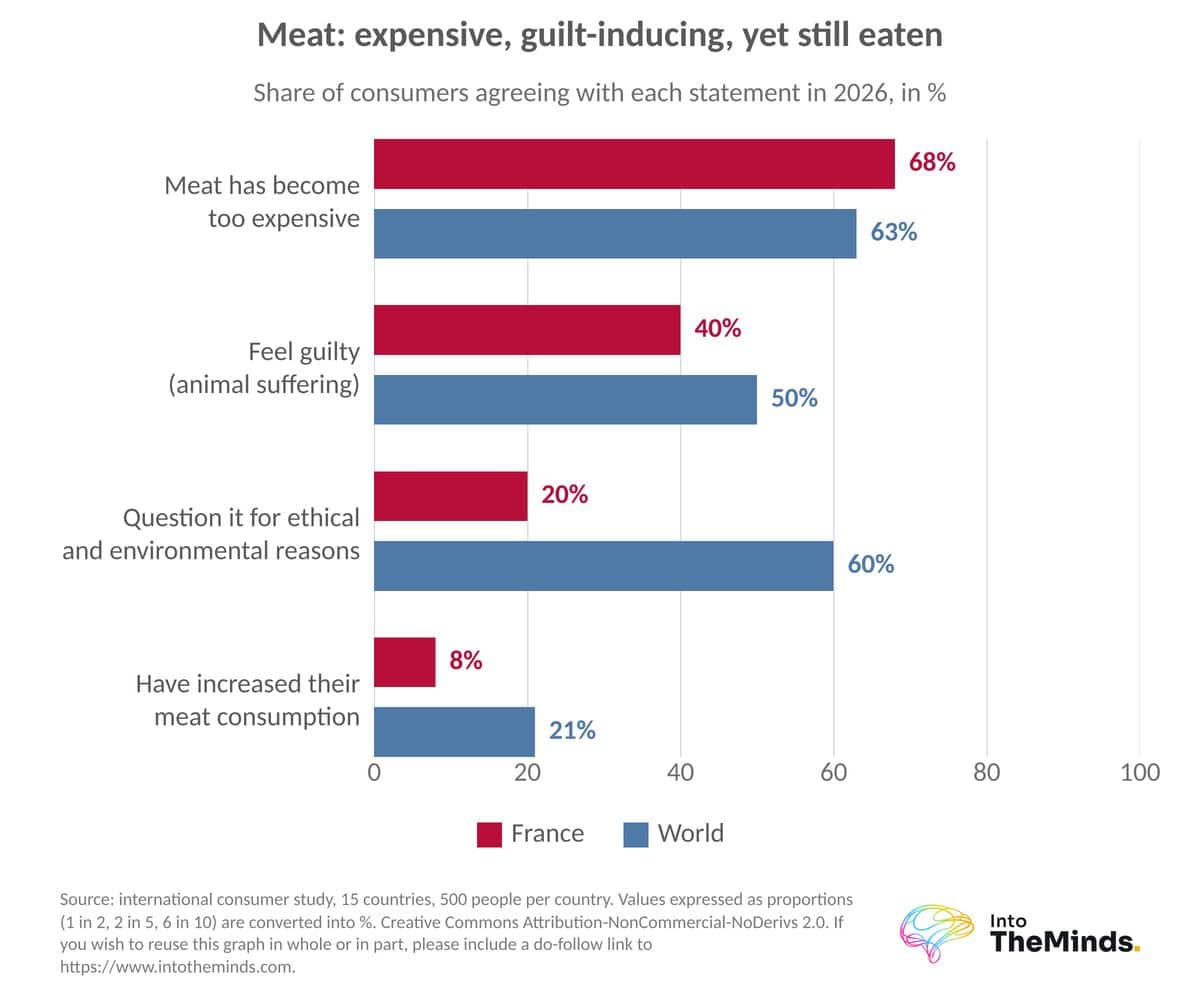
| Reduced consumption of animal protein | A more nuanced picture: 44% of consumers worldwide identify as flexitarians (2024), but 21% say they increased their meat consumption (2026). |
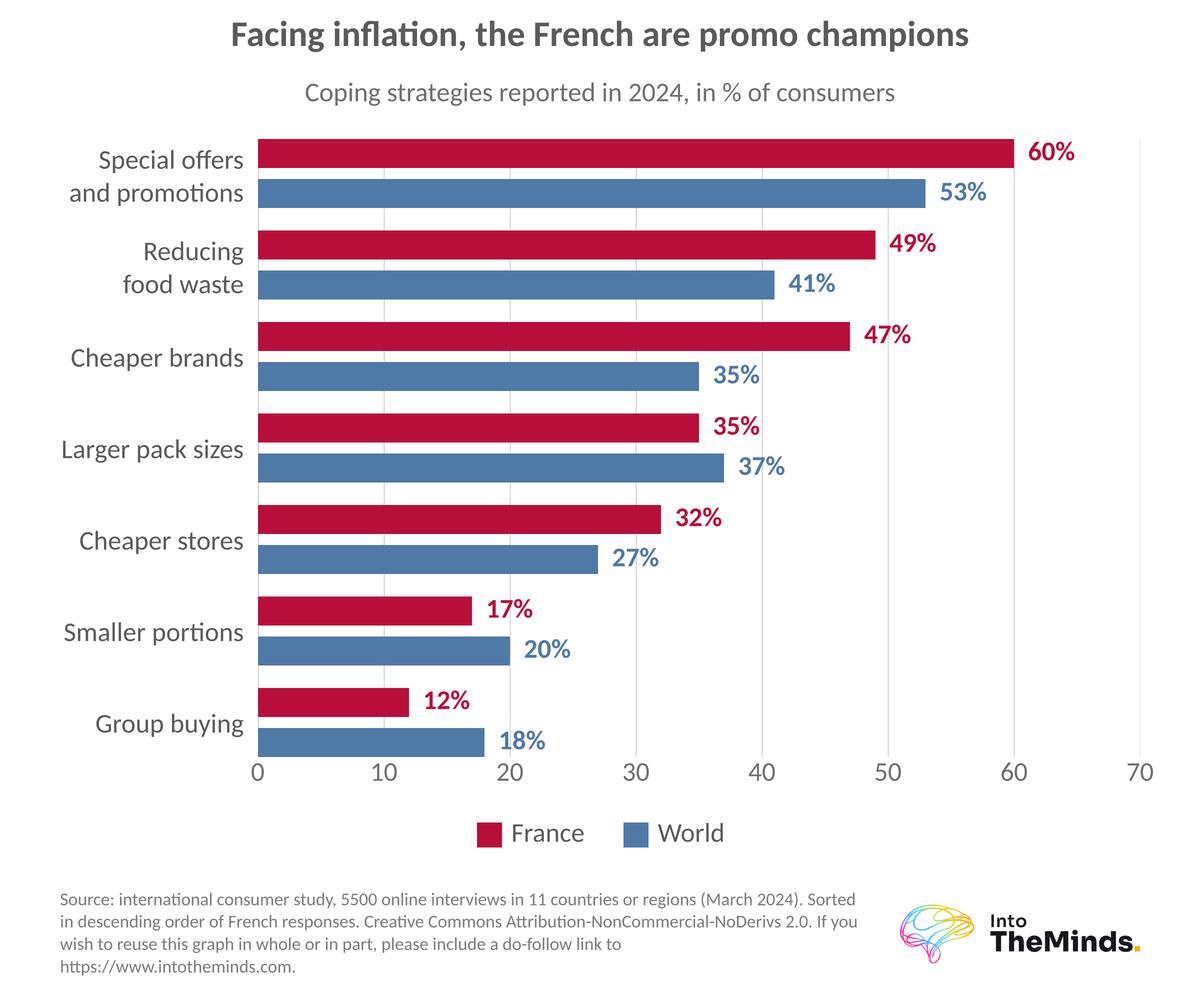
| The strategic consumer | Fully confirmed: price has become the leading indicator of quality (42%, +7 percentage points in 2024), and 60% of French consumers prioritise promotions. |
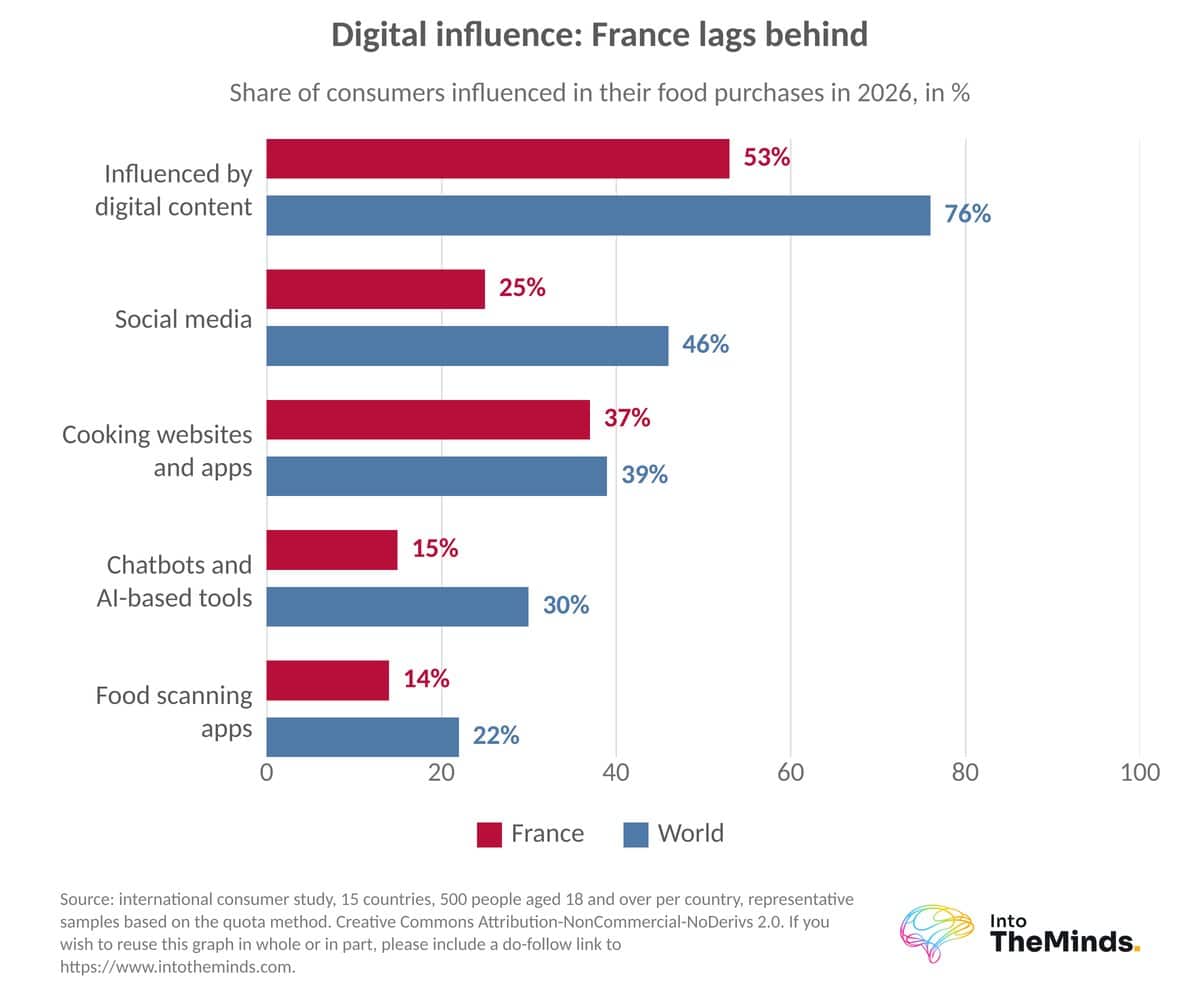
| Digital technology and food | Confirmed, particularly outside France: 76% of consumers worldwide say digital content influences them, compared with 53% in France (2026). |
| Do-it-yourself | Strengthened by inflation: 81% of French consumers believe cooking at home helps them control their spending (2024). |
| Individualisation | Confirmed: targeted product claims are multiplying (the number of products dedicated to women’s health doubled between 2021 and 2025), and 20% of consumers buy smaller portions (2024). |
| Reducing food waste | Confirmed: 41% of consumers worldwide and 49% of French consumers reduce food waste to cope with inflation (2024). |
| Nostalgia and authenticity | Reinvented for a younger audience: “newstalgia” is spreading on TikTok and Instagram, and 37% of consumers cite traditional dishes as a source of pleasure (2024). |
| New experiences linked to globalisation | Confirmed: 95% of consumers are interested in at least one foreign cuisine (2026), and exotic products gained 3.1 percentage points worldwide between 2021 and 2025. |
| Greater transparency | Under pressure: 90% of consumers expect ingredients to be guaranteed safe (2026), but labels are becoming less important as indicators of quality (34%, -2 percentage points in 2024). |
| Ready-to-eat food | Less significant than expected in France: 12% of consumers worldwide increased their purchases of ready meals, compared with 5% in France (2026). |
| Local sourcing and proximity | Confirmed: 71% of consumers worldwide prefer products from their region, compared with 63% in France (2026). |
| The search for naturalness | Losing ground in product offerings: naturalness declined by 6.5 percentage points in global innovations and by 12.5 percentage points in France between 2021 and 2025, even though 72% of consumers prefer minimally processed foods to avoid controversial ingredients (2024). |
| Seeking new consumption occasions | Confirmed: 45% of consumers in Europe and the United States snack at any time of day (2025). |
As this table shows, most of the predictions have been borne out. However, the 2024–2026 data indicate that the centre of gravity has shifted towards pleasure, functionality and price.
In food industry trends, the centre of gravity has shifted towards pleasure, functionality and price.
Food Industry Trends Are Evolving at Different Speeds
To understand where the country you are studying is heading, you first need to look at the global picture. This section presents the distribution of innovations across major world regions, followed by 3 countries with contrasting trajectories.
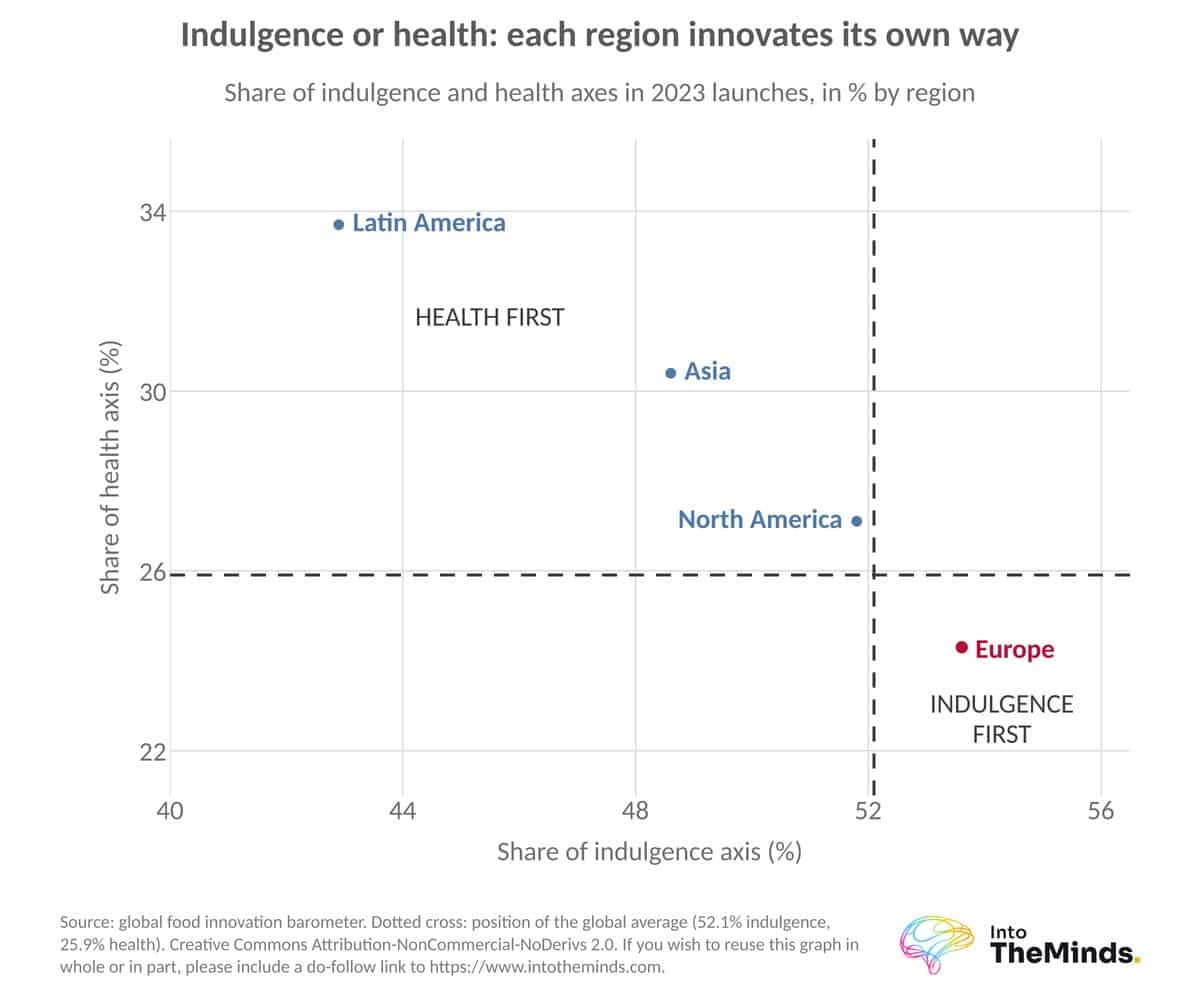
We compiled and analysed data from the global food innovation barometer, which classifies all product launches each year according to 5 dimensions: pleasure, health, fitness, convenience and ethics.
| Innovation dimension (2023) | Worldwide | North America | Latin America | Asia | Europe |
|---|---|---|---|---|---|
| Pleasure | 52.1% | 51.8% | 42.9% | 48.6% | 53.6% |
| Health | 25.9% | 27.1% | 33.7% | 30.4% | 24.3% |
| Fitness | 9.4% | 10.7% | 11.7% | 12.5% | 8.3% |
| Convenience | 6.3% | 3.7% | 6.3% | 5.0% | 7.0% |
| Ethics | 6.4% | 6.8% | 5.4% | 3.6% | 6.9% |
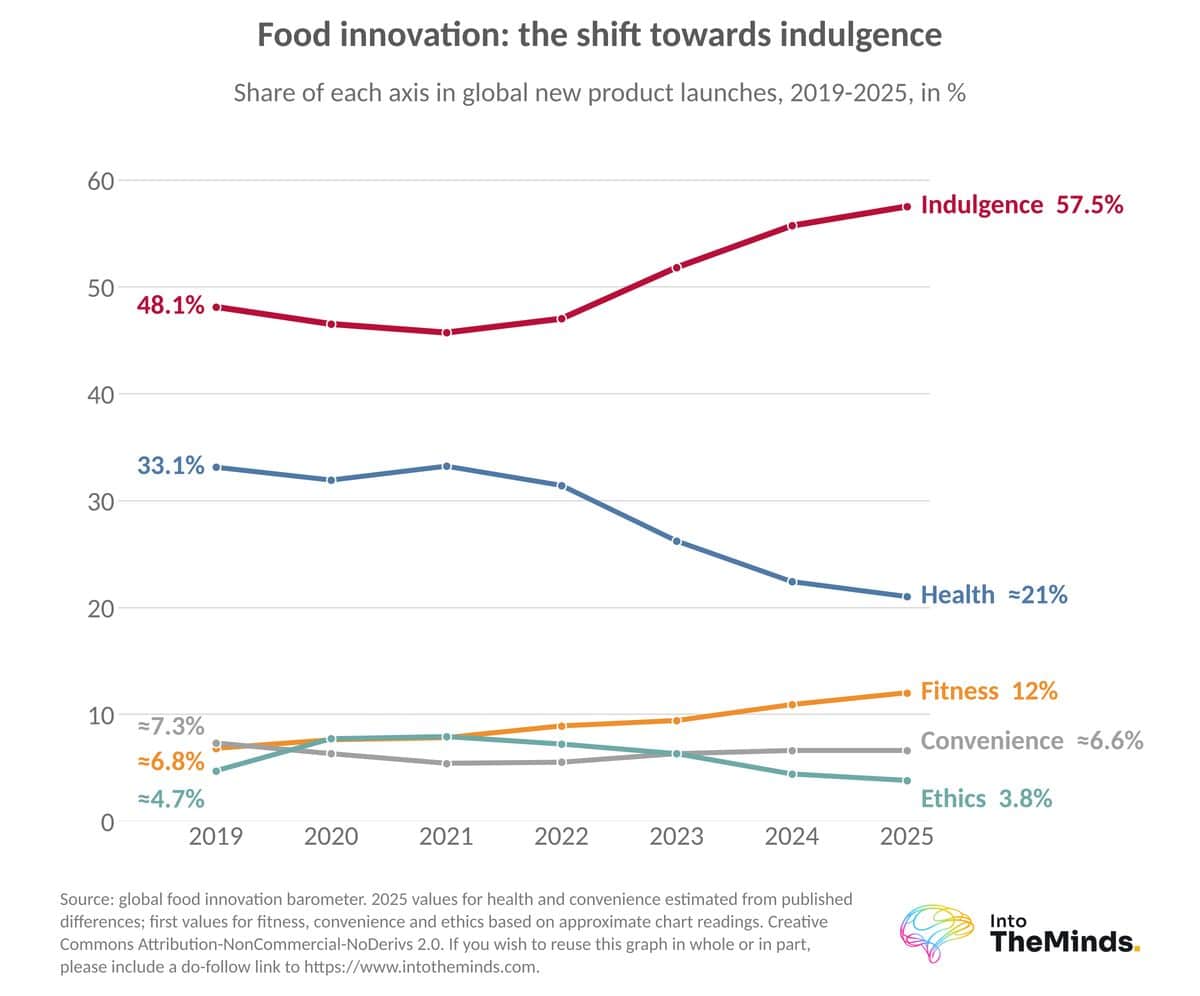
Pleasure, health and fitness dominate everywhere, but the balance varies. Latin America places the greatest emphasis on health, while Asia leads in fitness. Since then, the global shift has accelerated: pleasure rose from 45.7% of launches in 2021 to 57.5% in 2025, while health lost 10.3 percentage points over the same period.
To put this shift into perspective, the following chart traces the share of the 5 dimensions in global food innovation from 2019 to 2025.
In 2023, Europe was the region most focused on pleasure (53.6%) and the least focused on fitness. That year, sales volumes of fast-moving consumer goods fell by 1.4%. In 2025, across 6 major European markets, the average price of innovative products increased by 5.3%. European innovation is becoming more expensive, and brands will need to justify this premium.
France: A Trend That Amplifies Global Developments
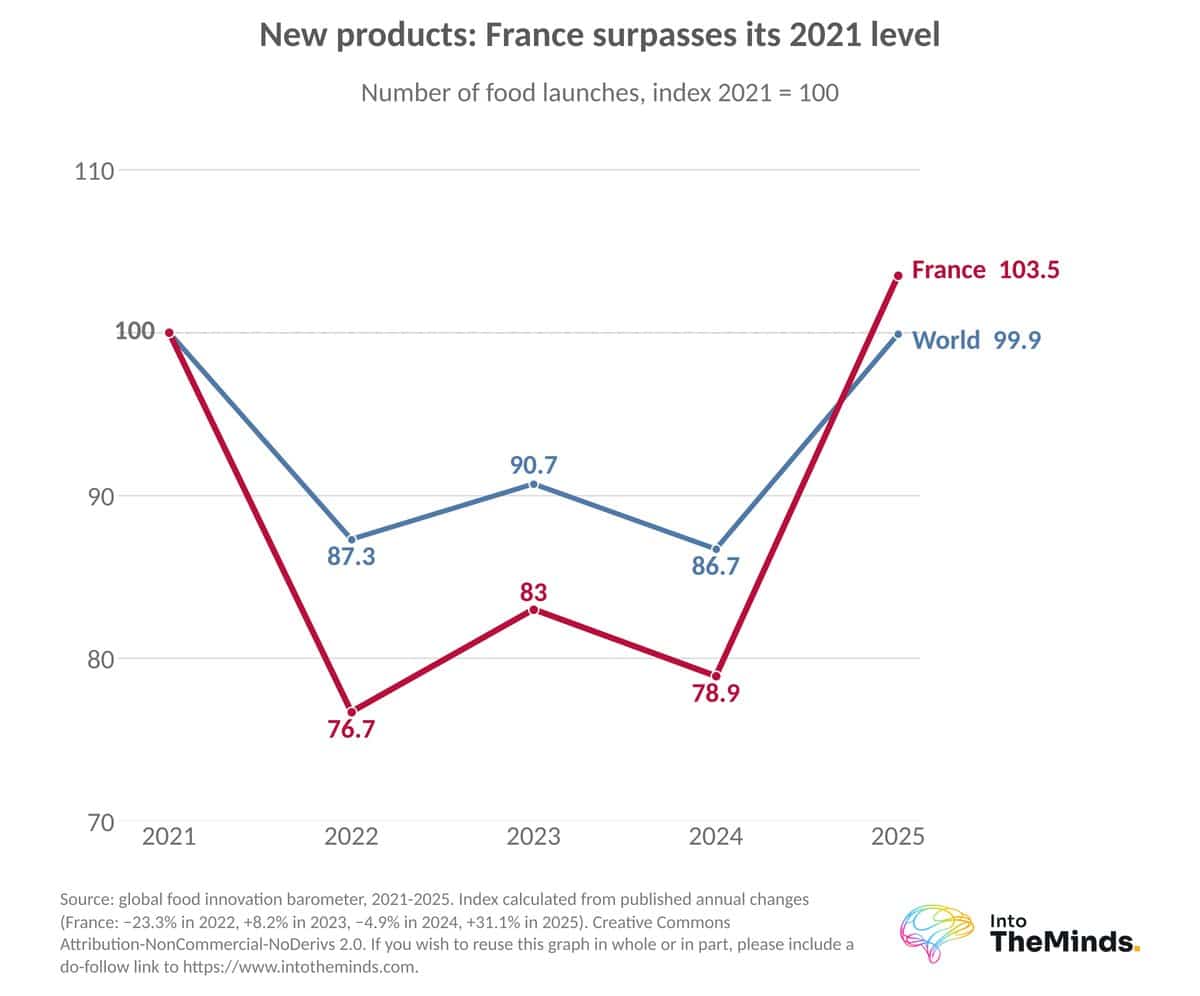
France is following global trends, but they are more pronounced there. New product launches in France fell by 23.3% in 2022, before rebounding by 31.1% in 2025. The volume of new products is approximately 3.5% higher than it was in 2021.
Pleasure accounted for 63.9% of French innovations in 2025. Ethics fell to 4.8%, compared with 10.1% in 2022, and naturalness lost 12.5 percentage points between 2021 and 2025.
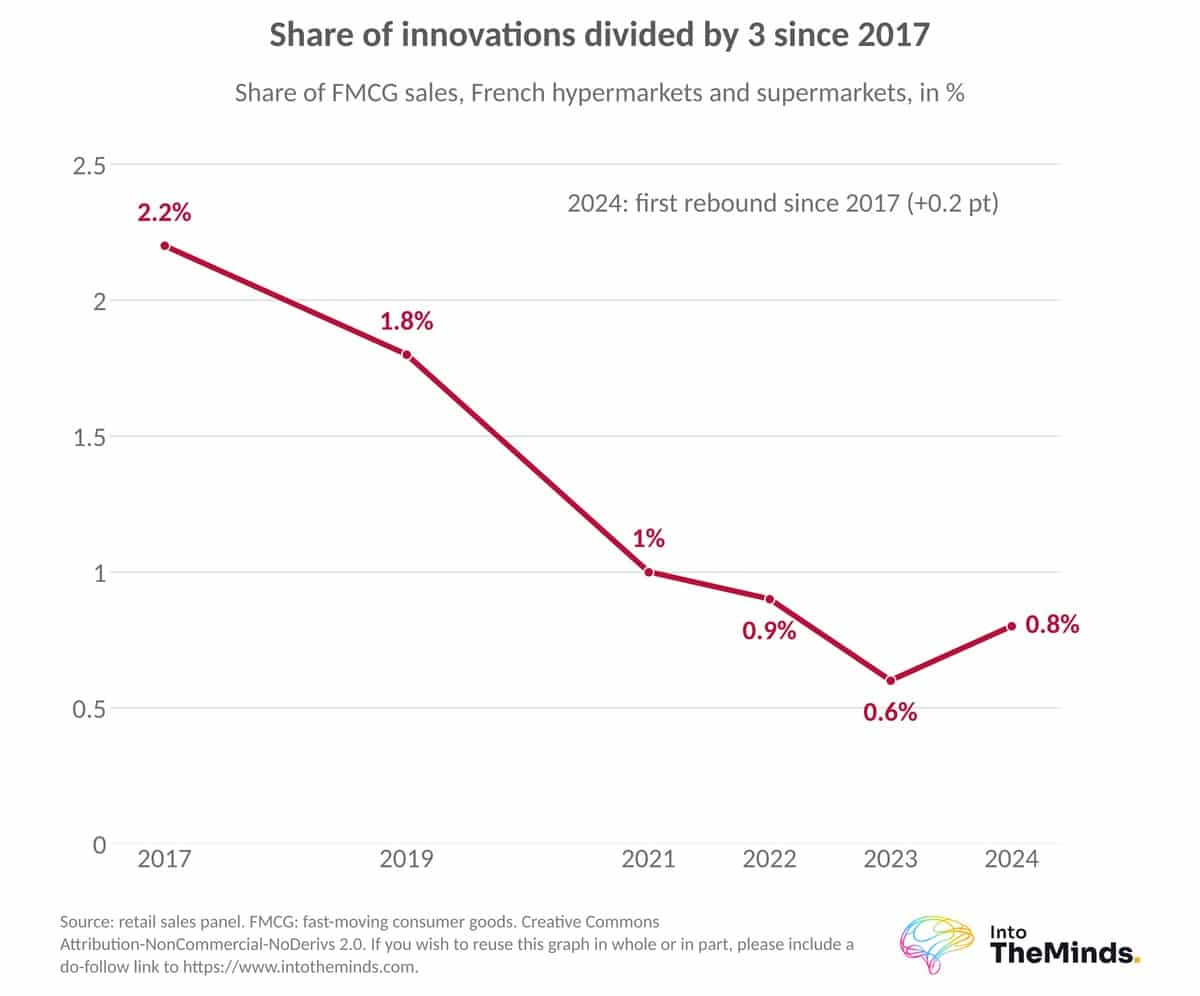
However, these innovations are struggling to sell. The share of innovations in fast-moving consumer goods revenue generated by hypermarkets and supermarkets fell from 2.2% in 2017 to 0.8% in 2024. The survival rate of new products is 81% after one year and 54% after two years (2025). Planning a 2-year action plan is no longer optional, and conducting market research beforehand is more important than ever.
United States: The Testing Ground for Functional Food
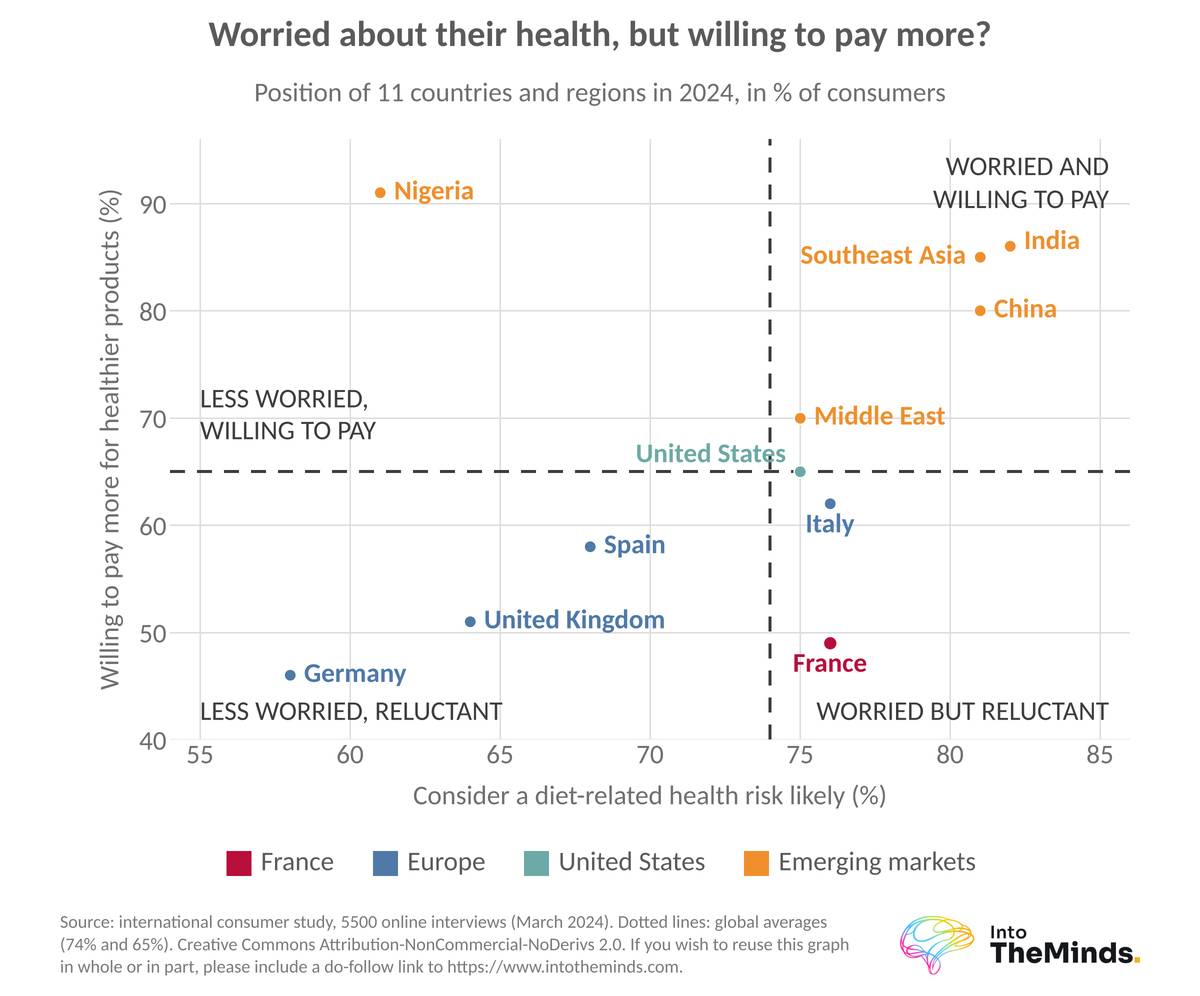
The United States is experiencing the fastest changes. In 2024, 75% of Americans considered it likely that their diet posed a risk to their health, 14 percentage points more than in 2022. The proportion willing to pay more for healthier products rose from 53% to 65% between 2022 and 2024.
GLP-1 drugs are accelerating this shift. According to a 2026 US study, 54% of people who were or had been taking these medications reduced their food intake, while 53% chose products with higher nutrient content. The United States remains the main source of functional food trends that subsequently spread to Europe.
Germany: A Market Driven by Price and Hard Discount Retailers
Germany stands out as a market where pleasure is less prominent. In 2024, 68% of Germans allowed themselves small food-related luxuries, the same level as in 2022. Only 46% were willing to pay more for healthier products, and the preference for products without colourings or preservatives fell from 64% to 55% in 2 years. The country is distinguished by its reliance on cheaper retail channels, supported by the strong presence of Lidl, Aldi and Action. Yet nearly one in two Germans reported following a specific dietary pattern in 2024, ranging from flexitarian to vegan.
In 2025, 57.5% of new food products launched worldwide focused on pleasure.
Pleasure Is Once Again Consumers’ Top Priority
This section shows that pleasure is the only area in which consumer expectations and manufacturers’ offerings are growing together.
A Return to Small Luxuries Despite Inflation
Worldwide, 75% of consumers treated themselves to small luxuries in 2024, compared with 70% in 2022. In 2026, the figure remained at 3 in 4 consumers, and 78% associated food with comfort in 2024.
In France, 72% of consumers indulged in these small luxuries in 2024, representing a return to the level recorded in 2018. During the inflation shock, comfort food became the last bastion of consumer spending. In 2023, crisp sales volumes rose by 25%, sweets by 16% and chocolate spreads by 15%. Yet fast-moving consumer goods as a whole declined by 3.1%. Pleasure-oriented products priced between €2 and €3 continued to grow.
Affordable pleasure has become a safe haven.
Pleasure is the only area in which consumer expectations and manufacturers’ offerings are growing together.
Intensity, Nostalgia and New Experiences Linked to Globalisation
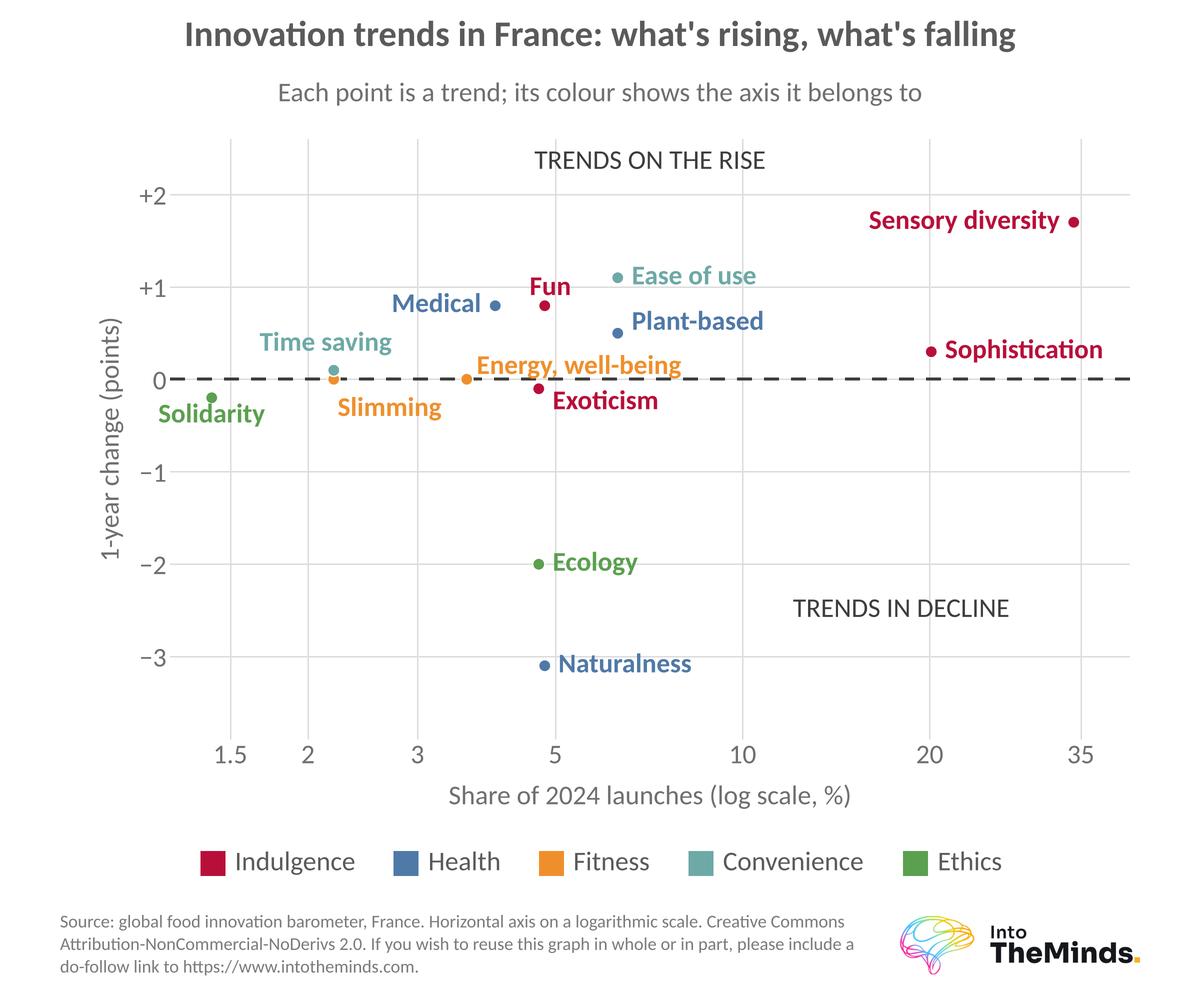
The codes of pleasure are changing. They are moving away from sophistication in favour of fun and intense sensations. Worldwide, products whose packaging emphasises intensity increased by 28%, while those highlighting chilli increased by 22.8%. Sensory stimulation was a defining feature of 34.9% of product launches in 2024.
Nostalgia and authenticity are returning in a more youthful form. An analysis of TikTok and Instagram conducted in France in early 2024 identified the concept of newstalgia: familiar flavours reimagined, such as matcha flan. Hyacinthe Parmentier (1883) and Puget (1857) have teamed up to offer sardines priced at €1.99, while Cacolac is celebrating its 70th anniversary with a Barista range.
New experiences linked to globalisation are becoming more targeted. In 2026, 95% of consumers were interested in at least one foreign cuisine, and exotic products gained 3.1 percentage points in global product launches between 2021 and 2025.
Health and Well-Being: From General Promises to Measurable Benefits
Health remains a major consumer concern, but expectations are becoming more specific. Consumers increasingly look for products that offer tangible benefits, such as improved energy, better digestion or higher nutritional value, rather than broad health claims.
Functional Food and Fermented Products
Functional food is gaining ground as manufacturers seek to combine pleasure with measurable benefits. Fermented products are among the categories benefiting from this trend. In France, sales of kefir and kombucha rose by between 149% and 168% in 2025.
Protein: Diversification Rather Than a Complete Shift Away from Meat
The relationship between consumers and animal protein is becoming more complex. Flexitarian diets are gaining ground, but consumers are not necessarily abandoning meat. Price, taste and convenience often matter more than dietary principles alone.
The share of consumers worldwide who identify as flexitarians or who are reducing their animal protein intake rose from 35% in 2020 to 44% in 2024. Yet innovations involving plant-based substitutes declined by 30% between 2021 and 2025. An oversupplied market is consolidating, while plant-based food is increasingly an adaptive choice rather than a strict dietary regime. In Europe, consumption of vegetarian substitutes rose by 16% in volume in 2025.
France has an ambivalent relationship with meat. In 2026, 68% of French consumers considered meat too expensive, and the proportion of flexitarians rose from 30% in 2020 to approximately 39% in 2024. Unit sales of pulses increased by 6% over the 12 months to the end of April 2026, three times the average growth rate for grocery products. Price is pushing consumers towards legumes more than personal conviction is.
The main protein diversification approaches observed include:
- Hybrid products: Ferrero launched Nutella Plant Based on 4 September 2024, using chickpeas and rice syrup instead of powdered milk. Materne adds 3% to 10% vegetables to its fruit purées.
- Microalgae: Algama replaces eggs with chlorella and reports 82% lower greenhouse gas emissions and 66% lower water consumption.
- Precision fermentation: Standing Ovation raised $34.2 million in March 2026 to produce casein, with Bel and Danone Ventures involved.
- Mycoprotein, combined with vegetables and legumes in Zyrcular Foods’ Amara Green burger.
Plant-based products can therefore be said to coexist with meat rather than replace it.
Persistent Inflation Is Changing Innovation Strategies
Food inflation reached historic levels in 2022 and 2023. In France, food prices in retail distribution rose by 13% in 2023 alone and by 20% over two years. This section shows who benefited from this trend and how consumers adapted.
Private-label brands account for 87% of the growth in unit sales of consumer goods in Europe.
Private-Label Brands: The Biggest Winners from Inflation in Europe
| Indicator | Europe | France |
|---|---|---|
| Private-label market share, 2023 | 39% | 36.5% |
| Growth in sales value, 2023 | +12% | +14% |
| Market share, 12 months to the end of February 2026 (6 major countries) | 42.4% | not reported |
| Contribution to revenue growth, end of February 2026 | 54% | not reported |
| Change in volume, 12 months to the 6th period of 2025 | not reported | +1.2% compared with -0.1% for national brands |
| Momentum in early 2026 | The Netherlands and Spain lead, ahead of the United Kingdom and Germany | Behind these 4 countries, at the same level as Italy |
In Europe, private-label market share has gained more than 3 percentage points in 3 years (see our study of the private-label market). The Netherlands and Spain showed the strongest momentum in early 2026. To say the least, this market is attracting considerable interest: 54% of consumer goods revenue growth comes from private-label brands.
In France, national brands have only one lasting response: differentiated innovation. BN’s Del’Ice, launched in April 2025, attracted 456,000 buyers and gained 1.5 percentage points in penetration in 3 months. Their weakness remains the speed with which retailers and new entrants copy their innovations. Measuring your brand’s position against private-label brands through a brand awareness survey helps determine whether this difference is visible on the shelf.
Affordable added value is becoming the main field for innovation: an additional benefit at an accessible price. A 130-gram Meelk container can be used to make 3 litres of plant-based drink, at €2.50 per litre, while Lustucru sells tagliatelle at prices 20% below the average.
Consumers Are Using Price as an Indicator of Quality
Worldwide, price became the leading indicator of quality in 2024 (42%, +7 percentage points), ahead of brand (35%), labels (34%, -2 percentage points) and information on packaging (33%). The strategic consumer described in the 2017 trend profile has become a reality.
| Responses to inflation (2024) | Worldwide | France |
|---|---|---|
| Special offers and promotions | 53% | 60% |
| Reducing food waste | 41% | 49% |
| Choosing cheaper brands | 35% | 47% |
| Buying larger pack sizes | 37% | 35% |
| Shopping at cheaper stores | 27% | 32% |
| Buying smaller portions | 20% | 17% |
In France, the proportion of supermarket customers who reported cutting back on consumption rose from 47% to 61% between 2022 and 2023. The difference between lower-income households (73%) and wealthier households (46%) is substantial. Cooking at home has benefited from this shift: in 2024, 81% of French people believed that cooking for themselves helped them control their spending.
Local Food, Sustainable Eating and Food Waste: Commitment Moves Closer to the Plate
Consumers are not abandoning their commitments. They are changing their focus, and this is where France differs most from the rest of the world, as we will see.
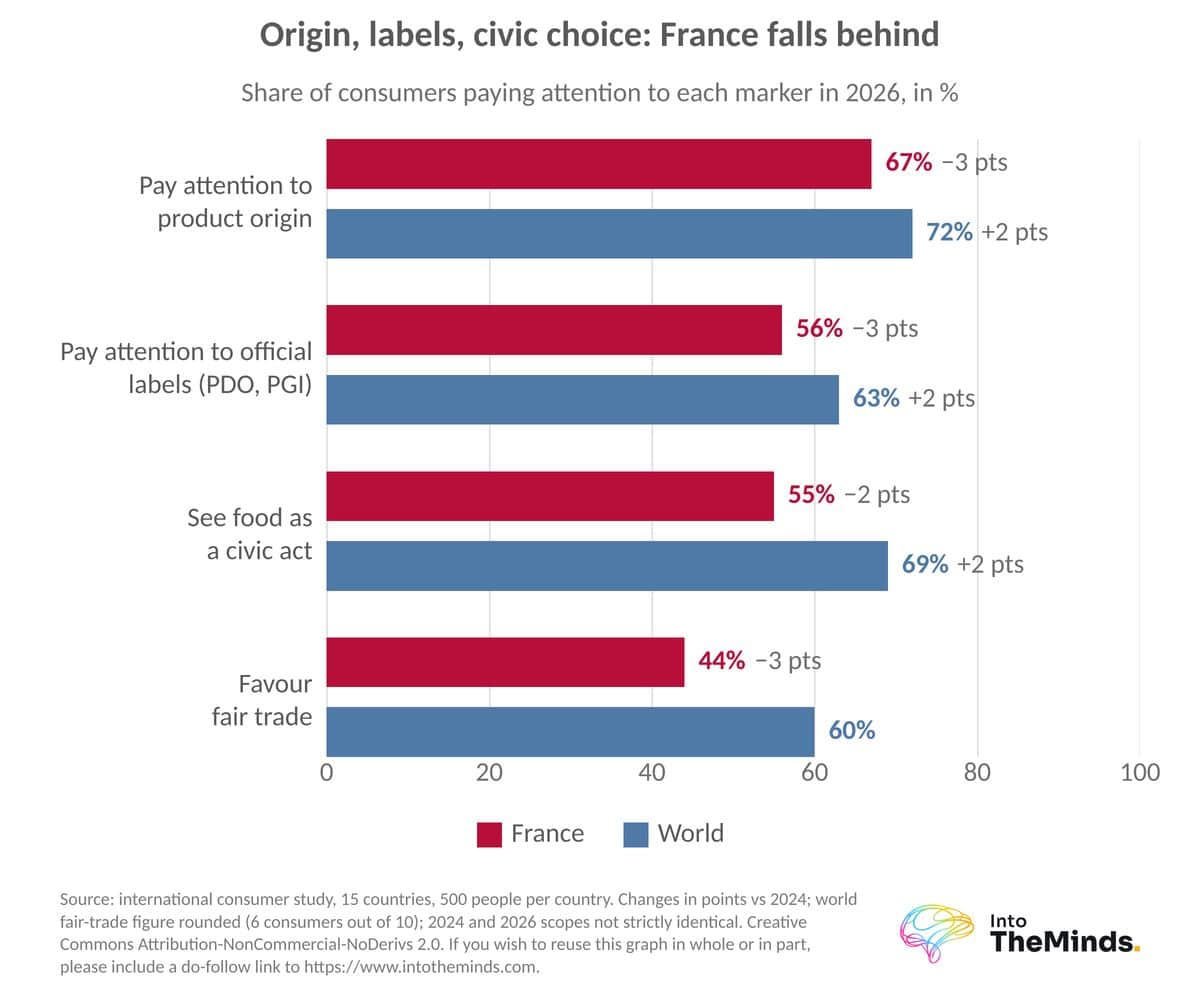
Worldwide, 71% of consumers prefer products from their region in 2026, and 69% consider food consumption an act of civic responsibility. In 2024, 63% preferred products with a low carbon footprint. Ethical offerings, however, accounted for just 3.8% of product launches in 2025. Sustainable food claims are becoming a basic requirement built into the recipe rather than a selling point. In 2026, 90% of consumers expect ingredients to be guaranteed safe, and 85% expect complete traceability from farm to plate.
France is falling behind on these indicators. In 2026, 63% of French consumers preferred products from their region, 67% paid attention to origin (-3 percentage points), and 56% considered official quality labels important (-3 percentage points). Organic food is paying the price: in 2024, only 15% of French consumers associated it with quality, and 62% said they would choose it in 2026 if it were cheaper. We see this as a sign of saturation in quality labels and indicators.
Transparency is achieved through other tools. According to Santé publique France, nearly 6 in 10 French people have changed their consumption after taking the Nutri-Score into account. The voluntary Origin’Info label, launched in May 2024, identifies the origin of the 3 main ingredients in processed products.
Food waste is declining for economic as well as environmental reasons. Efforts to reduce it have lowered sales volumes, and this trend is expected to continue. Manufacturers are investing in reusable packaging, such as Bonàrea’s RetornA deposit-return trays, which can be reused up to 50 times in Spain.
6 brands born on social media generated €100 million in French grocery retail in 2025.
Digital Channels and Influencers Are Changing How Consumers Discover Products
A food product’s visibility is now established before consumers enter the store. The table below shows the gap between France and the rest of the world.
| Digital influence on food purchases (2026) | Worldwide | France |
|---|---|---|
| Influenced by digital content | 76% | 53% |
| Social media | 46% | 25% |
| Cooking websites and apps | 39% | 37% |
| Conversational agents and artificial intelligence | 30% | 15% |
| Nutrition analysis apps | 22% | 14% |
Online grocery shopping has a long history in France. The world’s first drive-through grocery collection service was launched in 2004 in Marcq-en-Barœul. In 2023, online sales of food and consumer goods grew by 11%, according to Fevad. Online commerce was also the only channel to grow in volume (+0.9%). In stores, however, innovation remains hard to spot: 60% of French consumers discover new products in-store, but only 14% said they had noticed an innovation in 2025.
Influence creates brands. Squeezie’s Kombucha, MrBeast’s Feastables and Franui’s chocolate-covered raspberries are among the 6 brands that generated €100 million in French grocery retail in 2025.
Foodservice: A Slow Recovery and Lasting Trade-Offs
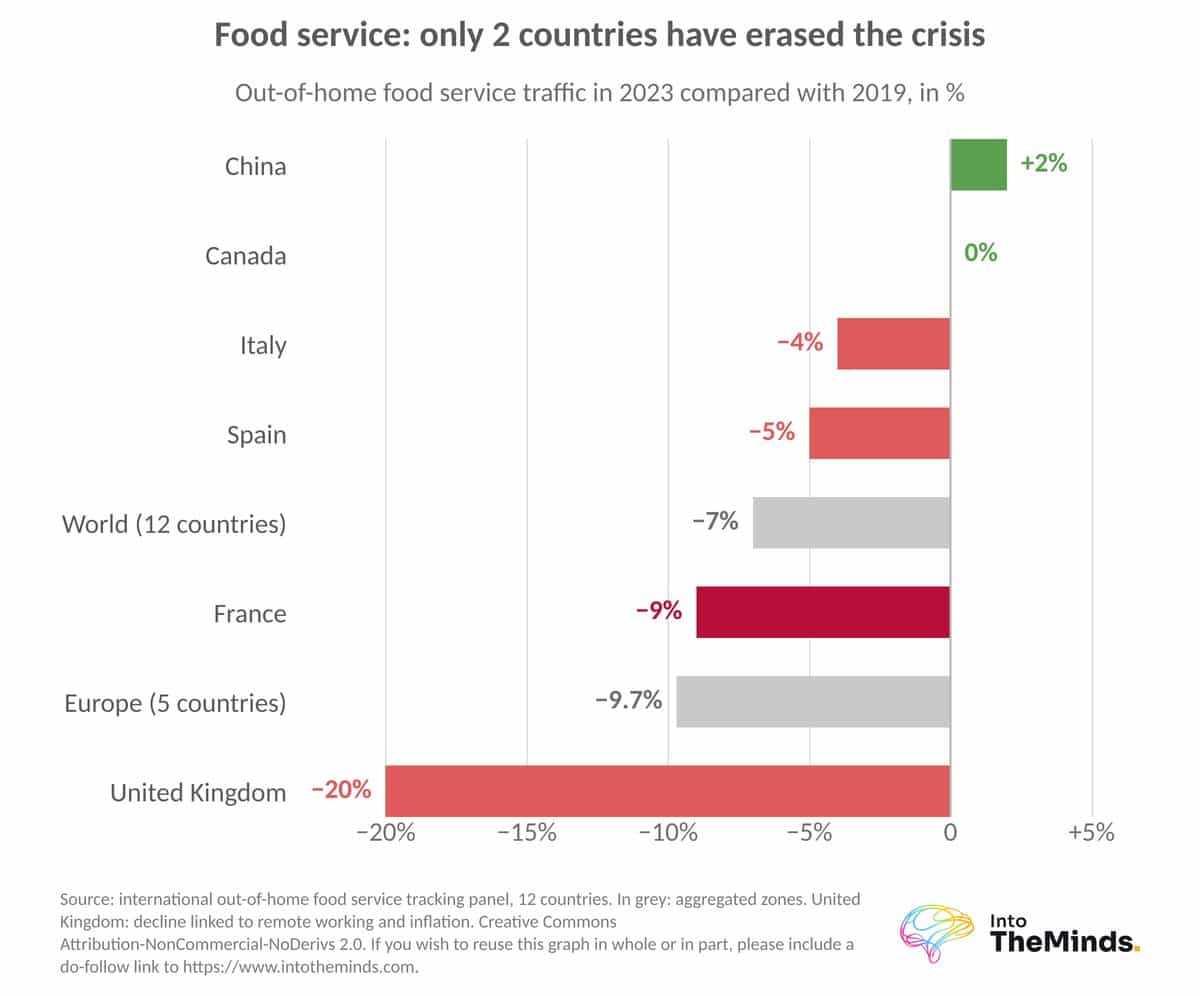
Eating out remains a social pleasure, but it comes at a higher price. The following figures help quantify this trade-off.
Across the 5 major European countries, out-of-home foodservice spending rose from €309 billion in 2019 to €323 billion in 2023, driven by higher average spending per transaction. Yet customer traffic remained 9.7% below its 2019 level. In 2024, 52% of Europeans believed restaurant prices had risen too much. Snacking accounted for 59% of European foodservice in 2025, while traditional table-service meals continued to lose ground.
In France, customer traffic in 2023 remained 9% below its 2019 level, with remote working accounting for 7 of those 9 percentage points. 60% of French consumers choose restaurants based on affordable prices. Ready-to-eat food is growing more slowly than elsewhere: only 5% of French consumers increased their purchases of ready meals in 2026, and 4% replaced meals with snacks. Special diets are becoming more common, with 56% of French consumers expecting restaurants to offer menus compatible with a variety of dietary requirements. The meal ritual remains firmly established in France.
Looking Ahead to 2028: What Food Industry Players Need to Anticipate
The trends measured between 2022 and 2026 point to several likely developments. Below are the directions supported by the strongest signals.
Less Severe Inflation, but a Lasting Presence
The 2022 crisis provides a clear indication of the effects of a price shock. Product launches fell by 12.7% worldwide and by 23.3% in France, while more expensive “transition” products were the first to be sacrificed: naturalness lost 6.7 percentage points in French product offerings in a single year. In 2026, inflation is easing, but purchasing power remains under pressure, and private-label brands account for 87% of the growth in unit sales in Europe.
By 2028, their growth is expected to continue at a pace similar to that of the past 3 years, as long as inflation remains entrenched. Affordable added value should become the main area of innovation for national brands. The average price of innovative products in Europe rose by 5.3% in 2025: this premium will need to be justified by a benefit consumers can immediately perceive.
Global Warming: From Raw Material Risk to Product Selling Point
The early heatwaves of 2025 placed 3 ice creams and 3 chilled drinks among the 20 best innovations of the first half of the year in France, while hydration tablets are now being targeted at heatwave periods. Cocoa, grown in distant regions and subject to sharp inflation, is already inspiring substitutes: ChoViva, made from sunflower seeds and adopted by Kaufland in Germany, and Épât’moi spread, made from carob, a tree that requires very little water.
Climate-related innovations most likely to succeed will also be those that lower prices. Algama, mentioned above, claims savings of 27% to 40% compared with eggs. Environmental benefits are likely to return to innovation through economic arguments rather than activism. The carbon footprint, which experts consider a key future indicator of responsible consumption, could nevertheless lose credibility if it proliferates without a common benchmark, just as quality labels have done.
Measurable Health Benefits, Accelerated by GLP-1 Drugs
The spread of GLP-1 drugs beyond the United States is expected to accelerate demand for smaller portions, higher nutritional density and satiety. Protein-rich offerings will remain abundant at least until 2027, with Danone’s capacity expansion in Ferrières-en-Bray and Sodiaal’s protein-processing facilities coming online. Fibre and digestive health could then take over, building on the wave of fermented products.
Artificial Intelligence: The New Recommender
In 2026, 30% of consumers worldwide already rely on conversational agents or artificial intelligence tools when making food choices, compared with 15% in France. Since only 14% of French consumers notice innovations on store shelves, product discovery is expected to continue moving upstream, before shoppers reach the store. Brands will need to appear in the answers provided by digital assistants, not just on shelves.
Three Scenarios for 2027–2028
The table below summarises three possible trajectories and the signal to monitor in each case.
| Scenario | Assumption | Likely impact on innovation | Signal to monitor |
|---|---|---|---|
| Persistent constraints (central scenario) | Moderate but persistent inflation, with occasional climate-related shocks affecting certain raw materials | Continued but selective launches, focused on pleasure, functional benefits and fair pricing | Private-label market share in Europe |
| Another price shock | Raw material prices surge because of climate, energy or geopolitical factors | A decline in launches comparable to 2022 (-12.7% worldwide), with transitional products cut first | Cocoa and meat prices |
| Improving conditions | A sustained decline in inflation and rising wages | Trading up and a return to organic products: 67% of consumers would buy more if organic food were cheaper (2026) | Organic food sales and restaurant traffic |
The United States and Asia Lead the Way, While Europe Faces Constraints
The United States is expected to remain the testing ground for functional food. India, Southeast Asia and Nigeria, where 85% to 91% of consumers said in 2024 that they were willing to pay more for healthier products, are the markets most receptive to premium health-focused products. Europe remains the region most sensitive to price. France is likely to continue following global trends with a delay but with greater intensity, while maintaining its commitment to the meal ritual and showing more limited digital influence.
Several milestones will help test these assumptions: SIAL Paris, from 17 to 21 October 2026, with 8,000 exhibitors expected; the expansion of protein-production facilities in 2027; and the next edition of the major international consumer study, published every two years, in 2028.
Our recommendation is simple: test every new product’s pleasure promise and price before launch, then monitor its performance for 2 years. A B2C market research study conducted beforehand helps you avoid joining the 46% of innovations that fail to make it through their second year.
FAQ: Frequently Asked Questions
What are the 16 key trends in the food industry?
These are the trends identified in 2017 by the forward-looking study conducted by the French Ministry of Agriculture in partnership with Ania, CGAD, CGI, Coop de France, FCD and FranceAgriMer. They range from sustainable food and the search for new consumption occasions to transparency, proximity and the strategic consumer. Each trend has its own trend profile and impact profile.
How has inflation changed eating habits?
It has intensified the search for promotions and cheaper brands. In 2024, 60% of French consumers turned to special offers and 47% chose cheaper brands. The proportion of customers reporting that they were cutting back on consumption rose from 47% to 61% between 2022 and 2023.
Why are private-label brands gaining ground in Europe?
Because consumers are making price-based trade-offs without giving up quality. Private-label brands reached a 42.4% market share across 6 major European countries in early 2026 and accounted for 54% of revenue growth. To understand professional buyers’ expectations in response to this trend, a B2B market research study involving retailers provides direct insight.
Does social media influence food purchases?
Yes, but much less in France than elsewhere. In 2026, 46% of consumers worldwide cited social media as a source of influence, compared with 25% in France. A survey of your target audience can help measure its actual influence on your products.
How can a food company anticipate these trends?
By combining monitoring of product offerings with listening to customers. The global food innovation barometer shows what competitors are launching, but only asking your buyers reveals what they expect. A customer satisfaction survey after launch helps you improve an innovation before its second year, when its long-term survival is decided.